Labels

Lifestyle (459) Investing (404) Entertainment (305) Singapore (261) Technology (150) Rewards (137) Insights (127) Gaming (104) Equities (97) AI (90) Data (86) Food (85) U.S. (77) Sports (74) Crypto (73) Travel (66) Portfolio (55) News (51) Credit Card (38) Earnings (36) Football (35) Movies (35) Savings (34) Property (28) Policies (27) Tennis (25) Shows (24) Holidays (23) Promotions (19) Bonds (16) Toys (16) Malaysia (15) World (15) REITs (14) T-Bills (12) Apps (11) China (11) Healthcare (10) Referral (10) Currency (9) Anime (8) DeFi (8) Retirement (8) CPF (7) Cash Management (7) Security (6) ETFs (5) Miles (5) Shopping (5) Commodities (4) Robotics (4) Weird (4) platform (4) Cashback (3) Insurance (3) Japan (3) Blog (2) Reviews (2) Robo-Advisor (2) 1-For-1 (1) Asia (1) Australia (1) Banking (1) Funds Management (1) Futuristic (1) Government (1) Indonesia (1) Inflation (1) Interesting (1) Nerfs (1) SGD (1) SSB (1) Social (1) Thailand (1)

Wednesday, 7 October 2026

Gaming Updates: New Crossy Road game announced as an Apple Arcade exclusive


Source:


ChatGPT:


I checked the 9to5Mac article and the wider discussion around the announcement. Since this was announced only 6 October 2026, the social-media footprint is still quite small, so the sentiment score should be treated as an early read, not a settled consensus. (9to5Mac)

🎮 What the article is about

The article announces Crossy Road Rush, a new spin-off from Hipster Whale, coming exclusively to Apple Arcade on 5 November 2026. (9to5Mac)

It takes the familiar Crossy Road characters and voxel-style presentation but changes the gameplay considerably:

  • Arcade-action/platforming runner

  • Solo Adventure mode

  • 50+ handcrafted levels

  • Daily Survival mode

  • Bosses, enemies and environmental hazards

  • Character/board unlocks

  • Up to 4-player local or online multiplayer

  • Global leaderboards

  • No ads or in-app purchases as part of Apple Arcade. (The Mac Observer)

The basic story involves helping the Crossy Road Crew defeat the Octoboss, rescue friends and restore Crossy Cove. (9to5Mac)

So this isn't simply:

"Crossy Road gets more levels."

It's much closer to a full-fledged Crossy Road action/adventure spin-off.


🆚 How different is it from the original?

This is probably the most interesting part.

The original Crossy Road is basically:

tap → hop → avoid traffic → survive

Crossy Road Rush moves towards:

run → jump → dodge → fight → explore → collect → cooperate

It therefore appears to borrow more from the Crossy Road Castle evolution of the franchise than simply extending the original game.

That makes sense because Crossy Road Castle was also an Apple Arcade exclusive when it launched in 2020. (9to5Mac)

The difference this time is that Rush appears to lean even more heavily into short-form obstacle-course/racing gameplay and multiplayer. Pocket Gamer describes it as moving toward a more traditional endless-runner structure. (Pocket Gamer)


🍎 Why Apple Arcade is important here

This is actually a bigger Apple Arcade story than a Crossy Road story.

Apple Arcade has been increasingly using recognisable franchises and exclusive versions to give the subscription a reason to exist.

Crossy Road is a particularly good fit because the franchise already has strong recognition among:

  • children

  • families

  • casual gamers

  • iPhone/iPad users

And Apple Arcade gives it a major advantage:

No ads + no IAP

That's particularly attractive for parents.

The service currently has 200+ games, and Crossy Road Rush joins several other October/November additions. (9to5Mac)


👨‍👩‍👧‍👦 For your family, this is actually quite relevant

Given that you have children who play iOS games, I'd put this into the "worth watching" category.

The combination of:

simple controls + colourful characters + 4-player multiplayer + no IAP

is almost tailor-made for family play.

The 4-player local/online multiplayer is probably the strongest feature for families. (9to5Mac)

And if you're already using Apple One/Apple Arcade, the marginal cost is effectively zero.

If you're not an Apple Arcade subscriber, however, I wouldn't subscribe just for this one game yet.


💬 What is the online reaction?

Here's where things get interesting.

🟢 General gaming reaction: positive

The initial coverage is broadly enthusiastic.

Gaming sites are focusing on:

  • 50+ levels

  • four-player multiplayer

  • the familiar Crossy Road IP

  • Apple Arcade's no-IAP model

  • the shift toward a more substantial adventure. (The Otaku Authority)

There isn't much evidence yet of a significant backlash.

But there's an important caveat:

The game hasn't launched.

So most of the current "sentiment" is really announcement/trailer reaction, not reviews from people who have played it.


🔴 The potential criticism: "Why Apple Arcade exclusive?"

This is the biggest issue I would watch.

The original Crossy Road was a hugely successful free-to-play mobile game.

Apple Arcade exclusivity means people who want Rush but don't subscribe to Apple Arcade won't simply be able to buy/download it normally.

That's not a new strategy for Apple. Crossy Road Castle previously followed the same route. (9to5Mac)

And there is evidence that some players have already questioned the value of Apple Arcade exclusivity for earlier Crossy Road releases.

For example, reviews of Crossy Road+ have complained that the Apple Arcade version didn't feel sufficiently different from the original to justify being a separate Arcade title. (App Store)

That doesn't mean Rush will suffer the same problem — it appears to have substantially more new gameplay — but it's a potential perception problem.


🟡 Reddit

I couldn't find a sizeable Reddit discussion specifically about Crossy Road Rush yet.

That's actually significant.

For a game announcement this new, the absence of a large Reddit discussion suggests:

It's interesting to Crossy Road/Apple Arcade fans, but it isn't currently breaking out into a major gaming conversation.

The strongest discussion is likely to emerge closer to launch on 5 November, when people can actually play it.


🟡 HardwareZone

I also couldn't find a meaningful current HWZ thread specifically discussing Crossy Road Rush.

This is consistent with the Reddit picture.

Singapore's tech/gaming community isn't treating this as a major gaming event yet.

The likely HWZ discussion, if one develops, will probably be around:

  • Is Apple Arcade worth paying for?

  • Is this suitable for kids?

  • Can four people play together?

  • Apple One value

  • Apple Arcade exclusives

  • whether Apple is taking games away from the normal App Store.


📱 X / Facebook / Instagram / TikTok / Threads

There's currently no evidence of a major viral conversation around the announcement on these platforms.

The important distinction is:

High promotional interest

Apple / Hipster Whale / gaming sites are pushing the announcement.

Low organic viral interest

There isn't yet a large wave of people saying:

"OMG I need this!"

That's quite normal for a casual-game announcement made only one day ago.

The game's potential for TikTok/Instagram is actually quite good, though, because short multiplayer clips, funny deaths and four-player chaos are naturally shareable.


🧠 The bigger Apple strategy

This announcement fits a broader Apple Arcade strategy.

Apple doesn't necessarily need every Arcade game to become a blockbuster.

Instead, it wants a library containing:

recognisable IP + family games + premium indie games + ad-free versions + exclusives

Crossy Road Rush ticks several of those boxes.

And the timing is interesting because Hipster Whale was acquired by Atari in 2026, with Atari paying an initial US$29.3 million and potential additional earnouts. (Mobilegamer.biz)

That gives Atari/Hipster Whale another way to monetise the Crossy Road brand while avoiding traditional mobile free-to-play monetisation for this particular title.


📊 My sentiment & impact scores

CategoryScore / 10
Overall sentiment8/10 positive
Crossy Road fan reaction8.5/10
Apple Arcade subscriber reaction8.5/10
Family/kids appeal9/10
General gamer interest6.5/10
Social-media buzz4/10
Reddit buzz4/10
HardwareZone buzz3/10
Controversy3/10
Apple Arcade strategic value8/10
Potential for family multiplayer9/10
Overall news impact5.5/10

⭐ Sentiment: 8/10 positive

⭐ Impact: 5.5/10

My verdict

Good Apple Arcade news, but not a major gaming-industry story.

The most attractive aspect isn't simply that there's a new Crossy Road game. It's that Crossy Road Rush looks like a substantial evolution of the franchise rather than a lightly repackaged mobile game.

The combination of 50+ levels + survival mode + bosses + exploration + 4-player multiplayer gives it considerably more substance than a basic Crossy Road re-release. (The Otaku Authority)

For your family specifically, I'd upgrade its attractiveness to about 8.5/10 because the four-player, family-friendly, no-IAP design fits very well with casual iOS gaming.

The question I'd wait to answer is:

Is Crossy Road Rush good enough to make a non-Apple-Arcade user subscribe?

Right now, probably not by itself.

But if you already have Apple Arcade through Apple One, this looks like a very easy game to put on the family's November watchlist.
Property Updates: Johor-Singapore SEZ Property Prices Are Up 7–9% — But Investors Still Face One Big Risk


Source:


ChatGPT:


I reviewed the 6 Oct 2026 Stacked Homes article, its underlying Savills data, and the wider Singapore/Johor property discussion. The article is quite nuanced: Johor's JS-SEZ story is improving, but the old oversupply problem has not disappeared. (Property Blog Singapore - Stacked Homes)

🏠 What the article is saying

The headline figures are attractive:

  • JS-SEZ residential prices: up roughly 7–9% YoY

  • Johor overall: only about 2–4%

  • JS-SEZ rental yields: around 6–8%

  • Johor overall: around 5–6%

  • Growth is being supported by corporate/expat rental demand, particularly around major employment and transport nodes. (Property Blog Singapore - Stacked Homes)

The nine JS-SEZ flagship areas include:

JB Waterfront, Iskandar Puteri, Tanjung Pelepas, Tanjung Langsat, Senai-Skudai, Kulai-Sedenak, Desaru-Penawar, Forest City and Pengerang. (Property Blog Singapore - Stacked Homes)

The article's central thesis is that a new type of Johor rental property may be emerging.

Rather than the old speculative "buy condo, wait for Singaporeans/Chinese buyers, sell higher" model, the new opportunity is supposedly:

well-managed properties close to actual economic activity, rented to companies, expats and skilled workers.

That means proximity to:

  • RTS / Bukit Chagar

  • JB CIQ

  • JB City Centre

  • Medini / Iskandar Puteri

  • major industrial/data-centre areas

is becoming much more important than simply buying a cheap condo somewhere in Johor.


⚠️ But the article's real message is the warning

This isn't really a "Johor property boom!" article.

It's more:

"Some parts of Johor are finally working — but don't confuse that with the whole market recovering."

Johor still has a large oversupply of residential units.

The article says around 9,972 unsold units remained in 1H2026, more than twice Kuala Lumpur's unsold stock. (Property Blog Singapore - Stacked Homes)

And there is another problem:

🚧 More supply is coming

Johor is expected to add around 115,000 homes by 2030, with roughly 70,000 in Johor Bahru.

EdgeProp's latest analysis says 609 projects are in the pipeline, with 244 of them in JB. (EdgeProp)

That creates a very interesting contradiction:

Demand ↑
RTS ↑
JS-SEZ investment ↑
Corporate tenants ↑

but simultaneously:

Housing supply ↑↑↑

That's why the article's warning about oversupply is important.


🚆 RTS is the big catalyst

The RTS is probably the single biggest property catalyst in the story.

It will eventually connect:

Woodlands North ↔ Bukit Chagar

in around five minutes on the rail journey.

The opening has now been pushed to February 2027, according to the article. (Property Blog Singapore - Stacked Homes)

This potentially creates a much larger pool of people who can:

work in Singapore → live in JB

or

work partly in Singapore / partly in Johor → rent in JB

That's especially important for corporate housing.

But Stacked makes an important distinction:

RTS doesn't automatically make every Johor property valuable.

A property 20 km away doesn't suddenly become a five-minute commute.


🏢 The "new asset class"

This is probably the most interesting part of the article.

Savills argues that certain properties could develop into a distinct corporate-rental asset class.

The characteristics are roughly:

✅ Good candidates

  • 1–3 bedroom units

  • within roughly 1–3 km of major employment/transport nodes

  • integrated developments

  • professional management

  • security

  • nearby supermarkets/F&B

  • good connectivity

  • international-school access

  • suitable for executives/expats

Examples mentioned include:

R&F Princess Cove, Suasana Iskandar, TriTower, Paragon Suites, Astake and Eco Botanic. (Property Blog Singapore - Stacked Homes)

❌ Riskier

  • isolated serviced apartments

  • generic investor condos

  • developments far from employment

  • huge developments with thousands of identical units

  • properties whose entire investment thesis is "RTS will make prices rise"

That distinction is extremely important.


💰 The 6–8% rental yield sounds great — but...

This is where I'd be particularly cautious.

A 6–8% gross yield is not the same thing as a 6–8% return in your pocket.

You have:

  • maintenance fees

  • property management

  • agent fees

  • vacancy

  • repairs

  • furnishing

  • taxes

  • potentially higher costs for serviced apartments

  • currency risk

  • resale/liquidity risk

EdgeProp quotes a current market warning that a 6.5% gross yield can potentially become around 4% net after costs. (EdgeProp)

That's a massive difference.

And there's another problem:

You may be buying today's high rent at tomorrow's high property price.

If property prices have already risen 7–9%, your yield on the new purchase price may be considerably less attractive than the yield enjoyed by someone who bought two or three years ago.


🌲 And then there's the Forest City lesson

This is probably the most important historical comparison.

Johor has been here before.

The earlier Iskandar boom attracted huge amounts of speculative capital and massive high-rise development.

Then foreign demand weakened, especially after China's capital controls and changing Malaysian policies around foreign ownership.

The result:

too many apartments + too few genuine residents = enormous oversupply.

Forest City became the most famous example.

And interestingly, even now, CNA reports that Forest City remains a buyer's market, with many sellers but relatively few buyers. (CNA)

So the JS-SEZ story isn't occurring in a vacuum.


💬 What are Singaporeans saying?

This is where the article gets particularly interesting.

🟠 HardwareZone: quite sceptical

HWZ's long-running JS-SEZ property discussions are much more bearish than the property industry's marketing material.

Common concerns include:

  • "Another Forest City?"

  • massive oversupply

  • difficulty reselling

  • Malaysian policy uncertainty

  • property management problems

  • foreign ownership restrictions

  • whether Singaporeans really want to live there

  • whether RTS benefits all developments or only the immediate corridor.

One particularly sceptical HWZ comment argues that Singaporeans shouldn't assume property ownership automatically gives them a long-term right to live in Malaysia and suggests renting rather than buying if the objective is simply to live in JB. (HardwareZone Forums)

The thread also has the classic counterargument:

RTS changes the equation because JB becomes much easier to access from Singapore.

So HWZ is basically:

"RTS is real, but don't get caught buying another Forest City."


Reddit: 🟡 cautiously sceptical

The Reddit discussion is similar.

A January 2025 r/SgHENRY discussion on the Singapore-Johor economic zone was quite negative, with concerns about:

  • policy uncertainty

  • corruption/business environment

  • immigration congestion

  • previous JB property failures

  • Singaporeans being marketed condos again. (Reddit)

Another r/singaporefi discussion produced a more nuanced debate.

Some users saw benefits from:

cheaper land + manufacturing + jobs + cross-border economic activity

while others worried about:

job competition + lower Singapore demand + housing effects + whether Johor actually captures the economic value. (Reddit)

And there is a particularly important social dimension: some Johoreans have already expressed concern that Singaporean/foreign buyers are pushing JB housing beyond the affordability of local residents. (Reddit)


📱 X / Facebook / Instagram / TikTok / Threads

There is much less independent discussion of this exact Stacked Homes article on these platforms than on Reddit/HWZ.

The conversation is currently dominated by:

property agents + developers + investors + Malaysia property accounts

rather than ordinary Singaporeans debating the article.

That's significant.

The article is therefore not yet a viral social-media story.

The discussion is still mostly happening among people who are already interested in:

  • JB property

  • RTS

  • JS-SEZ

  • Singapore retirement/relocation

  • Malaysian property investing.


🧠 My interpretation

I'd divide the Johor property story into three buckets.

🟢 1. RTS / CIQ / Bukit Chagar

Most convincing.

This is the part of the thesis I find strongest.

If you are within walking distance/easy access to:

Bukit Chagar → JB Sentral → CIQ → RTS

you have a genuine structural transportation advantage.

The five-minute RTS journey is a real infrastructure improvement.


🟢/🟡 2. Iskandar Puteri / Medini

More complicated.

There are legitimate economic drivers:

  • Legoland

  • international schools

  • healthcare

  • industrial/technology development

  • corporate tenants

But there's also a lot of existing and future supply.

So project selection matters enormously.


🔴 3. "Buy anywhere in Johor because JS-SEZ"

I would strongly reject this thesis.

This is where the article's warning about oversupply is most useful.

JS-SEZ is not a rising tide that automatically lifts every condo.

A cheap condo 15–20 km from the actual economic activity may remain a cheap condo.


📊 My scores

CategoryScore
Overall sentiment6.5/10 positive
Investor enthusiasm7/10
Reddit sentiment5.5/10
HardwareZone sentiment5/10
Property-industry sentiment8/10
Mainstream social-media interest4/10
Controversy5/10
Quality of investment information8/10
Impact on JB property8/10
Impact on Singaporeans considering JB8/10
Immediate buy/sell signal4/10
Long-term significance8/10

⭐ Overall sentiment: 6.5/10

⭐ Overall impact: 8/10

My verdict: This is a more important article than a simple "JB property prices rising" story.

The most useful takeaway is:

Johor may finally be transitioning from a speculative property story to an employment-and-rental-demand story — but only in selected locations.

That's a major difference.

Previously the thesis was:

"Singaporeans/foreigners will buy JB condos → prices rise."

The emerging JS-SEZ thesis is:

"Companies move economic activity into Johor → skilled workers/expats move there → genuine rental demand develops → selected properties become investable."

That second thesis is much healthier.

But I would still be cautious about the numbers because 6–8% gross yield + 7–9% capital growth sounds fantastic precisely when a large amount of new supply is coming. EdgeProp's 2026 pipeline of ~115,000 homes is the number I'd keep at the front of your mind. (EdgeProp)

If I were assessing JB purely as an investment today:

RTS/CIQ walking distance: 🟢 8/10

Strong employment node + quality development: 🟢 7.5/10

Iskandar Puteri/Medini selective buys: 🟡 6.5/10

Generic serviced apartment: 🟠 4/10

Remote condo bought purely for "JS-SEZ appreciation": 🔴 3/10

And given your family's Singapore base, I'd actually see JB as more compelling for a future lifestyle/second-home/geo-arbitrage option than as a straightforward passive property investment. The article itself provides a good reason: the strongest rental story is increasingly about where the jobs are, not simply where the condos are. (Property Blog Singapore - Stacked Homes)

Investing Updates: New ETFs Coming to SGX: S&P 500, NASDAQ-100 and MSCI World Explained


Source:


ChatGPT:


This is a meaningful development for Singapore ETF investors, and the online reaction is noticeably more substantive than the headline might suggest. The key issue isn't simply "four new ETFs"; it's whether SGX-listed, SGD-traded, Ireland-domiciled UCITS ETFs can become a practical alternative to buying CSPX/VWRA/etc. through LSE/IBKR.

📰 Article summary

The Smart Investor's 6 October article covers four Xtrackers UCITS ETFs from DWS that are scheduled to begin trading on SGX on 13 October 2026. (The Smart Investor)

SGX tickerExposureTERMain attraction
XUSS&P 5000.03%Very cheap US large-cap exposure
EUSS&P 500 Equal Weight0.15%Reduces mega-cap concentration
XNDNasdaq-1000.20%Tech/growth-heavy exposure
XWRMSCI World0.12%Developed-market diversification

All four are Irish-domiciled, accumulating UCITS ETFs, meaning dividends are reinvested rather than distributed. (The Smart Investor)

The headline attraction is that Singapore investors can now buy them in SGD on SGX, rather than accessing the LSE and converting SGD → USD/GBP first.

The tax angle is particularly important

The article argues that Ireland-domiciled ETFs are generally more tax-efficient for Singapore investors than US-domiciled ETFs.

For example, it compares:

S27 — US-domiciled S&P 500 ETF

vs.

XUS — Ireland-domiciled S&P 500 ETF

The article estimates that the combination of lower TER and lower dividend withholding-tax drag could save roughly 0.23 percentage points annually, or around S$230 per year on S$100,000 invested, based on its assumptions. (The Smart Investor)

That's potentially significant over decades.


🔥 But there's a much bigger story than the article

The real question being discussed online is:

"Should I now buy XUS/XWR on SGX instead of CSPX/VWRA through IBKR?"

And the answer from the investing community is basically:

Maybe — but don't sell your existing ETFs just to switch.

That's the dominant theme I've found.


💬 Reddit reaction

This is where the discussion is strongest.

The original r/singaporefi thread announcing the ETFs received 63 upvotes, with substantial discussion around:

  • XUS vs CSPX

  • XWR vs VWRA

  • SRS eligibility

  • SGX vs LSE trading

  • broker fees

  • liquidity

  • bid/ask spreads

  • CDP

  • SGD trading

  • currency risk. (Reddit)

That captures the sentiment quite well.

🟢 What's exciting investors

1. SRS

This may be the biggest practical advantage.

If you're investing through SRS, an SGX-listed ETF provides a much easier route to global equities than going through an overseas exchange. Redditors specifically highlighted the attraction of using XUS/XWR for SRS. (Reddit)

2. SGD trading

No need to manually convert SGD into USD before buying.

But there's an important misconception:

SGD-traded ≠ SGD-hedged.

XUS can be bought in SGD, but you're still exposed to the underlying US stocks and their currencies. (Reddit)

3. Ireland domicile

This retains the key tax advantage that Singapore investors already seek when buying CSPX/VWRA through the LSE. (Reddit)

4. Extremely low XUS TER

At 0.03%, XUS is unusually cheap.

That's even lower than CSPX's 0.07%. (The Kopi Notes)


⚠️ The biggest concern: liquidity

This is probably the single most important criticism.

CSPX has been trading on the LSE for years and has enormous liquidity.

The new Xtrackers SGX counters are starting from scratch on the Singapore trading line.

HardwareZone investors have already raised precisely this concern.

One HWZ discussion notes that S27 has substantially longer trading history and liquidity, while existing Xtrackers SGX listings such as XSG have relatively low volume. (HardwareZone Forums)

So:

XUS TER: 0.03%
CSPX TER: 0.07%

looks fantastic on paper.

But if XUS consistently has a materially wider bid/ask spread, that 0.04% TER advantage can become less meaningful.

That's why I would not automatically declare XUS superior to CSPX yet.

We need to see actual trading volume and spreads after 13 October.


🖥️ HardwareZone sentiment

The HWZ discussion is surprisingly balanced.

The overall attitude is:

👍 "This is good."

But followed immediately by:

🤔 "How liquid will it actually be?"

One HWZ participant described the growing ETF competition as good for retail investors, while another pointed out that investors shouldn't assume the new SGX ETFs will immediately match established LSE liquidity. (HardwareZone Forums)

Another very interesting HWZ discussion about XWR asks the obvious question:

Why not just have Vanguard cross-list VWRA?

That's telling.

VWRA remains the benchmark in many Singapore DIY portfolios.

XWR isn't equivalent to VWRA:

  • XWR = developed markets

  • VWRA = developed + emerging markets

So somebody moving from VWRA to XWR is actually changing their portfolio allocation, not merely changing the exchange. (HardwareZone Forums)


📊 Social-media / investing-community sentiment

I searched specifically for discussion around XUS/XWR/XND/EUS across the platforms you mentioned.

Reddit — 🟢 Strongly positive

This is currently the most active public discussion.

The tone is overwhelmingly:

"Interesting."
"Could be useful."
"Especially for SRS."
"Let's see the liquidity."

There is very little outright negativity. (Reddit)

HardwareZone — 🟢/🟡 Positive but pragmatic

More technically minded.

People are thinking about:

  • commissions

  • CDP

  • liquidity

  • bid/ask spreads

  • SRS

  • tax efficiency

  • broker selection.

This is probably the most useful discussion for actual Singapore investors. (HardwareZone Forums)

X / Twitter — 🟢 Positive but limited

There isn't yet a huge mainstream X conversation around the article itself.

The strongest social amplification is from the financial/investing ecosystem rather than ordinary retail investors.

Facebook — 🟡 Limited

I didn't find a significant public discussion specifically around this Smart Investor article.

Instagram — 🟡 Limited

Mostly informational/promotional content rather than detailed investor debate.

TikTok — 🟡 Limited

No meaningful volume of public discussion yet.

Threads — 🟡 Limited

Likewise, not enough discussion to suggest a strong independent sentiment.

Professional social media — 🟢 Strong

SGX itself is actively promoting the listing, emphasising SGD trading and SRS eligibility. (LinkedIn)

So the social-media picture is currently:

Investor forums >>> Reddit > professional social media >>> mainstream social media


🧠 The REALLY important comparison

For a Singapore investor, I'd frame the four ETFs like this:

ETFBest use
XUSCheap S&P 500 core
EUSReduce mega-cap concentration
XNDNasdaq/technology tilt
XWRDeveloped-world core
CSPXEstablished LSE S&P 500 option
VWRADeveloped + emerging global core

And XWR is not a VWRA replacement.

That's one of the biggest points being debated online.


💰 What this means for your portfolio

This article is actually particularly relevant to your investment setup because you've previously looked at Amundi MSCI World, global portfolios, IBKR and Singapore-listed ETFs.

I wouldn't interpret this announcement as:

"Sell existing global ETFs and buy XUS/XWR."

I'd interpret it as:

"Singapore investors now have another potentially excellent accumulation route."

For new money, the calculation becomes much more interesting.

If you want S&P 500

XUS becomes very compelling.

0.03% TER + Ireland domicile + SGD trading + potentially SRS eligibility.

But wait for actual SGX liquidity.

If you want developed-world diversification

XWR is interesting, particularly for SRS/CDP-oriented investors.

But don't confuse it with VWRA.

If you already use IBKR

The advantage is less obvious.

IBKR gives you:

  • LSE access

  • very deep liquidity

  • cheap FX

  • enormous ETF selection.

So the convenience of SGX doesn't necessarily outweigh IBKR's advantages.


📈 My sentiment & impact scores

CategoryScore / 10
Overall sentiment8.5/10 positive
Retail investor excitement8/10
Reddit sentiment8.5/10
HardwareZone sentiment8/10
Controversy2/10
Investment significance9/10
Impact on SGX8/10
Impact on SRS investors9/10
Impact on existing IBKR investors6/10
Impact on beginner investors9/10
Immediate market impact5/10
Long-term significance9/10

⭐ Overall sentiment: 8.5/10 positive

⭐ Overall impact: 8.5/10

My verdict: This is more important than the Smart Investor article makes it sound.

The article is basically a useful explainer, but the underlying development could be one of the more significant improvements to Singapore's retail ETF landscape in years.

The biggest winners are probably:

🥇 SRS investors
🥈 Beginners who want global exposure without LSE/FX complexity
🥉 Investors who want CDP-held global ETFs

The people who gain the least are experienced IBKR + LSE investors, because CSPX/VWRA and similar ETFs already give them excellent access and liquidity.

And there's one thing I'd watch very closely on 13 October:

XUS's actual bid/ask spread and trading volume.

If XUS develops decent liquidity, its 0.03% TER + Ireland domicile + SGX/SRS accessibility makes it a genuinely serious competitor to CSPX for Singapore investors.

If liquidity is poor, CSPX remains the better practical instrument despite its slightly higher TER.

So I'd call this 8.5/10 impact — but with a big "watch the liquidity" asterisk.

Rewards Updates: CapitaStar Turns 15 with Month-Long October Rewards and New Kris+ Integration


Source:


ChatGPT:


📰 Summary of the article

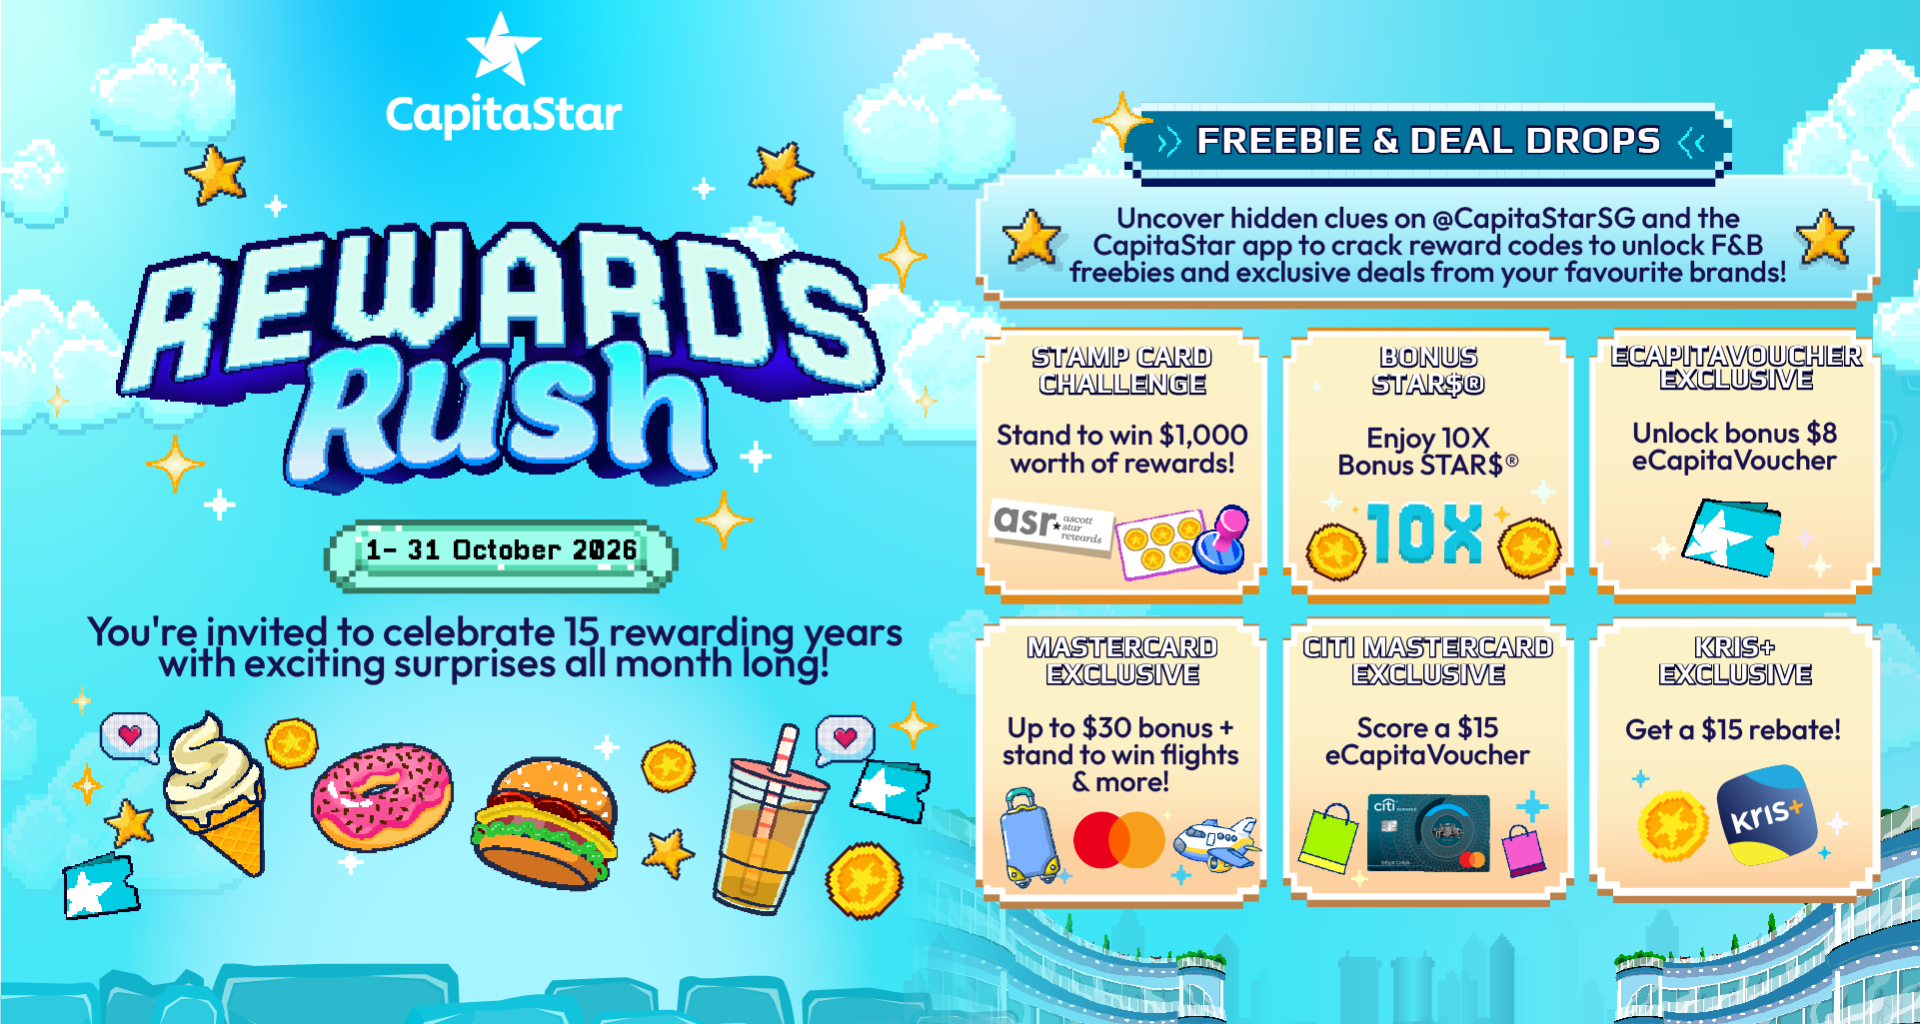
The Alvinology piece is essentially a promotion/deal roundup for CapitaStar's 15th anniversary, with the biggest development being the new CapitaStar × Kris+ integration. The underlying announcement was made by CapitaLand on 1 October, and the Alvinology article was published 6 October. (Alvinology)

The big news: CapitaStar + Kris+

This is the part I think is most relevant for you as a miles/rewards user.

After linking your accounts, you can now:

Pay with Kris+ → earn KrisPay miles + CapitaStar STAR$ in the same transaction.

Previously, using Kris+ generally meant giving up the ability to earn CapitaStar STAR$ on that transaction. The new integration removes that trade-off. (The MileLion)

There is a S$20 minimum transaction to earn STAR$ when paying through Kris+. (The MileLion)


🎁 October promotions

The article highlights several overlapping promotions.

1. S$150 Kris+ spend → 1,500 KrisPay miles

For 1–31 October 2026:

  • Link CapitaStar + Kris+

  • Spend S$150 in a single transaction

  • At an eligible Kris+ merchant in a participating CapitaStar property

  • Receive 1,500 KrisPay miles, effectively S$15 of Kris+ spending value.

There are 1,000 rewards available. Importantly, these particular 1,500 KrisPay miles cannot be transferred to KrisFlyer; they remain usable within Kris+. (The MileLion)

This is a very important distinction because the Alvinology article's wording about KrisPay/KrisFlyer can otherwise make the promotion look more valuable than it actually is.

2. 10X STAR$

October also gives 10X bonus STAR$ for qualifying S$80+ transactions using eligible linked payment methods, including Kris+. (The MileLion)

MileLion calculates that a S$100 transaction can generate roughly:

  • 500 base STAR$

  • 5,000 bonus STAR$

  • 5,500 STAR$ total

before assigning a value to the Kris+ miles. That's approximately a 5.5% CapitaStar rebate equivalent based on its calculation. (The MileLion)

3. eCapitaVoucher promotion

There is also:

S$80 eCapitaVoucher spend → 10X STAR$ + S$8 eCapitaVoucher bonus. (CapitaLand)

4. Mastercard promotion

Buy S$250 eCapitaVoucher with a linked Mastercard and you can receive up to S$30 bonus eCapitaVoucher plus entry into a lucky draw.

One of the prizes is 80,000 KrisFlyer miles.

Citi Mastercard users can also receive an additional S$15 eCapitaVoucher with S$200 qualifying in-store spend. (CapitaLand)

5. 15th anniversary prizes

15 winners get S$1,000 worth of STAR$ + Ascott Star Rewards points. (CapitaLand)


🔎 What is the online community saying?

The interesting thing is that this isn't really a mainstream news story. Discussion is concentrated among the Singapore miles/deals/loyalty-programme crowd.

🟢 Miles community: strongly positive

The reaction from the miles sites is clearly favourable.

MileLion's headline is basically:

"You can now double dip on Kris+ miles and STAR$."

Its conclusion is that STAR$ is a modest rebate, but since you're now getting it on top of Kris+ miles, there's little reason not to collect it when the transaction qualifies. (The MileLion)

Mainly Miles similarly describes it as a "double dip", particularly useful for people who regularly shop at CapitaLand malls such as Plaza Singapura, Raffles City and IMM. (Mainly Miles)

Suitesmile is also highlighting the S$15 rebate and how it can be combined with the broader Kris+ October promotions. (Suitesmile)

🟡 Reddit: more mixed

There isn't yet a significant Reddit thread specifically discussing the 6 October Alvinology article.

But there is a very relevant recent r/askSingapore discussion about Singapore loyalty apps. It received 92 upvotes, and the general assessment was that CapitaStar is more of a "collect passively and redeem periodically" programme, while Kris+ is more attractive to people who actively chase KrisFlyer miles. (Reddit)

That's actually a good description of the opportunity here:

CapitaStar alone: mildly interesting.

Kris+ alone: useful mainly to miles enthusiasts.

Kris+ + CapitaStar + suitable credit card: considerably more interesting.

🟡 HardwareZone: historically more sceptical/practical

The long-running CapitaStar thread on HardwareZone has a much more practical tone.

Users have discussed:

  • eCapitaVoucher usability

  • merchants not knowing how to process it

  • technical problems

  • whether STAR$ is worth using

  • changes to earning rules

  • stacking CapitaStar with other reward programmes.

One particularly relevant 2021 discussion reported merchants sometimes being unable to process eCapitaVoucher, while another user said they had never encountered such problems. (HardwareZone Forums)

More recently, HWZ users have complained about changes to CapitaStar earning and the difficulty of stacking it with other programmes. (HardwareZone Forums)

So the HWZ mentality is less:

"Wow, amazing new partnership!"

and more:

"Can I actually stack this with my existing cards/rewards and is the effort worth it?"

That's probably the right way to evaluate this promotion.

X / Facebook / Instagram / TikTok / Threads

I couldn't find a substantial, independently indexed discussion around this particular announcement on those platforms yet.

That's not surprising because the announcement is only about a week old.

There is, however, clear official/social amplification. CapitaLand is promoting the anniversary and Kris+ integration on LinkedIn, while CapitaStar is directing members to its Instagram account for the October treasure-hunt codes. (LinkedIn)

So the social conversation currently appears to be promotion-driven rather than controversy-driven.


💡 The part I think matters most for YOU

Given your existing interest in KrisFlyer + credit-card stacking + eCapitaVoucher, I'd actually rate the Kris+ integration more important than the 15th-anniversary celebration itself.

The new stack potentially becomes:

Credit card
↓
Kris+ miles
+
CapitaStar STAR$
+
October promotional bonus
+
potentially other card-specific rewards

That's significantly more interesting than CapitaStar's old model.

However, there's an important catch:

Don't automatically use Kris+ for every CapitaLand purchase.

You still need to compare:

Kris+ miles + STAR$

against what you'd earn using your best credit card directly.

And the biggest trap is the S$150 rebate.

It's not really:

"Spend $150 and get 1,500 KrisFlyer miles."

It's:

"Spend $150 and get 1,500 KrisPay miles that are worth S$15 within Kris+."

Those 1,500 miles cannot be transferred to your KrisFlyer account. (Singapore Airlines)

That's a very different proposition.


📊 My sentiment & impact score

CategoryScore / 10My assessment
Overall sentiment8.5/10 positiveMostly viewed as extra rewards
Miles-community sentiment9/10Double-dipping is genuinely useful
General consumer sentiment7/10Nice rewards, but requires spending
Controversy2/10Very little controversy
Deal attractiveness8/10Good if you're already spending at CapitaLand malls
KrisFlyer relevance6/10Better than before, but KrisPay ≠ KrisFlyer
CapitaStar relevance9/10Meaningfully improves the programme
Impact on Singapore consumers6/10Useful but not transformational
Impact on miles/points collectors8.5/10This is the target audience
Overall article impact7.5/10Useful deal news rather than major Singapore news

⭐ Sentiment: 8.5/10 positive

⭐ Impact: 7.5/10

My verdict

This is a genuinely useful rewards development, not just a CapitaStar birthday marketing exercise.

The CapitaStar × Kris+ double-dipping is the real story.

For someone who already shops at Lot One, Plaza Singapura, IMM, Junction 8, Tampines Mall, Westgate, etc., the integration gives you another reason to route eligible spending through Kris+.

But I'd rate the S$150 → 1,500 KrisPay miles promotion as good rather than exceptional, because the reward is locked inside Kris+ rather than becoming transferable KrisFlyer miles.

And given your previous strategy of saving your S$1,000 eCapitaVoucher rather than using it unnecessarily, I wouldn't change that strategy just because of this article. The better opportunity is to use new cash/card spending that you were already going to make and stack the rewards.

One particularly interesting angle for you: October 2026 has both the CapitaStar 15th-anniversary promotions and the Kris+ Birthday Bash (including 8 miles/S$1 at 65+ partners), so October is unusually attractive for people who are willing to optimise the payment method. (Singapore Airlines)

Lifestyle Updates: Singapore Ranks No. 1 In Asia Pacific For Next-Gen Wealth — But The New Rich Aren’t Investing Like Their Parents


Source:


ChatGPT:


I checked the Stacked Homes article against the underlying Savills report and looked for current discussion across Singapore forums/social platforms. The article is very new — published 5 Oct 2026 — so the social-media footprint is still relatively small. (Property Blog Singapore - Stacked Homes)

📰 What the article is saying

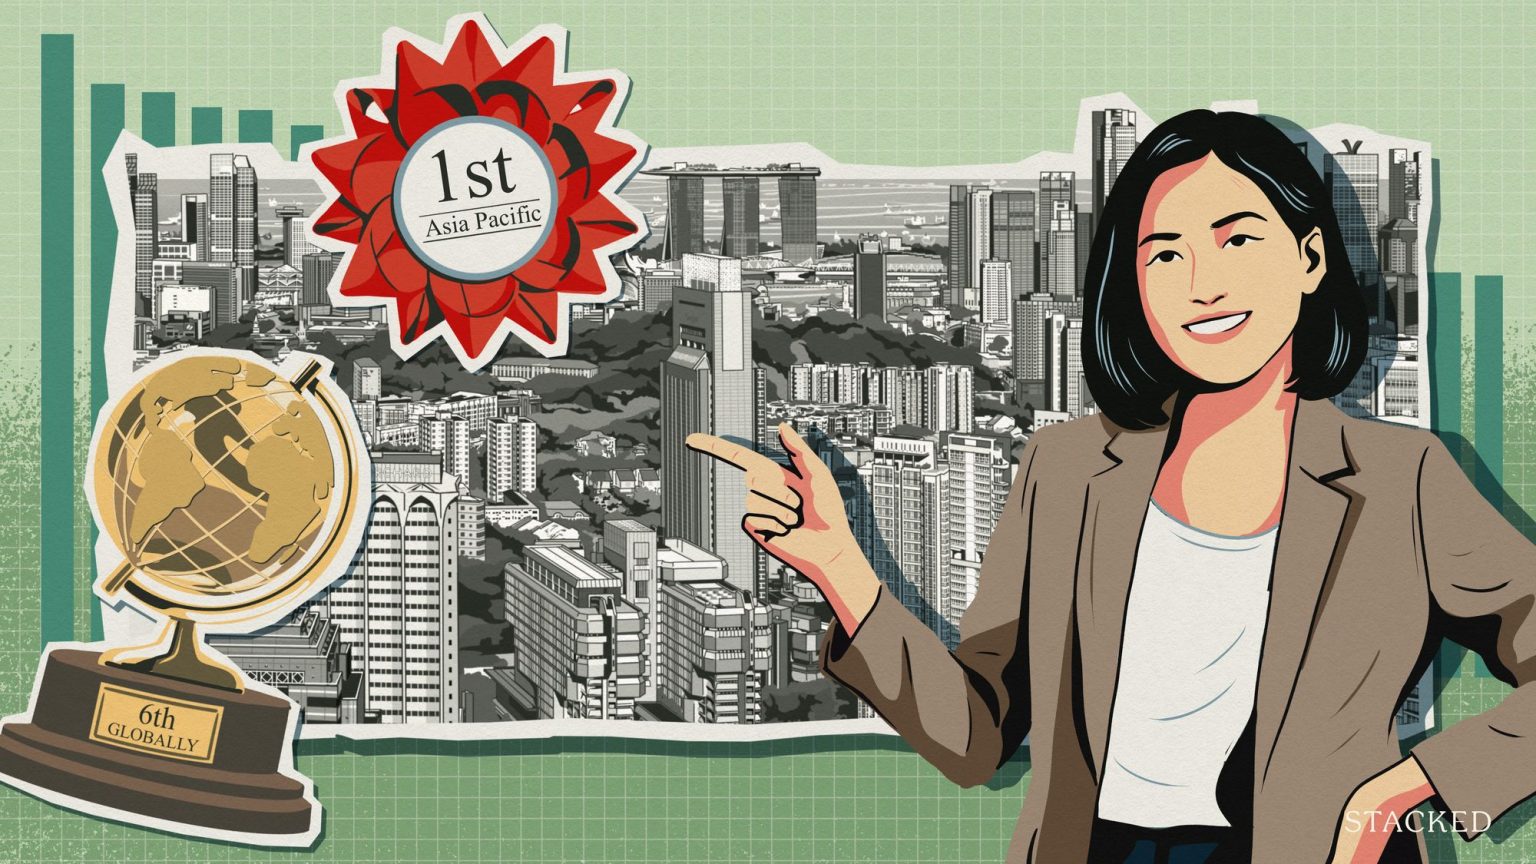
Main message: Singapore is extremely well positioned to attract the next generation of wealthy people, but the challenge is no longer simply getting rich people to put money here — it is getting their children and successors to stay here too.

Savills' new Next Generation Wealth Hubs Index ranks:

RankCity
🥇New York
🥈Miami
🥉London
4San Francisco
5Los Angeles
6Singapore
7Hong Kong
12Tokyo
18Shanghai
25Bangkok
29Kuala Lumpur

Singapore is therefore #1 in Asia-Pacific, ahead of Hong Kong. The index covers more than 100 wealth hubs and assesses four broad areas: business/governance/connectivity, wealth clusters/environment, wealth management/taxation, and lifestyle. (Savills Singapore)

The interesting part isn't actually the ranking

The more important point is that wealthy younger investors are changing how they invest.

Instead of the traditional:

Property → property → property

portfolio, the next generation is increasingly looking at:

  • Prime residential property

  • Equities

  • Venture capital

  • Private markets

  • Operating businesses

  • Technology/AI businesses

Real estate remains important, but increasingly as one component of a diversified wealth strategy, rather than the entire strategy. (The Business Times)

Why Singapore scores so well

The article/Savills point to Singapore's combination of:

  • political and legal stability

  • financial infrastructure

  • family offices

  • private banking

  • education

  • taxation environment

  • regional connectivity

  • lifestyle and safety

  • ability to manage wealth across generations

And this is becoming more important because an estimated US$84 trillion of wealth is expected to transfer between generations over the next two decades. (Savills Singapore)


🏠 What does this mean for Singapore property?

This is where Stacked Homes puts its own property spin on the Savills report.

The argument is essentially:

The wealthy aren't merely buying a condo. They're buying an ecosystem.

For wealthy families, property location increasingly needs to provide:

education + lifestyle + wellness + privacy + connectivity + investment access + succession planning

rather than simply:

"Can this condo appreciate 20%?"

This could favour prime, highly serviced, turnkey properties, branded residences and developments that appeal to internationally mobile wealthy families. Savills similarly says scarce, highly serviced assets in markets with legal stability, lifestyle quality, privacy and long-term liquidity are likely to be more resilient. (Savills Singapore)


🌏 But there's an important counterpoint

The article is somewhat property-industry friendly.

The headline makes it sound like:

"Singapore is No. 1 for next-generation wealth → therefore Singapore property is attractive."

But the underlying report actually says something more nuanced:

Next-gen wealthy investors are becoming less dependent on property.

That's quite important.

Savills itself says real estate is increasingly being considered alongside equities, private markets, VC and operating businesses. (The Business Times)

So I wouldn't interpret this report as:

"Singapore property prices will definitely rise."

I'd interpret it as:

"Singapore remains an attractive place for wealthy people to live, manage wealth and deploy capital — and that creates structural support for certain parts of the property market."

That's a much more defensible conclusion.


💬 What are Singaporeans saying?

Reddit / Singapore forums

I couldn't find a substantial Reddit thread specifically discussing this exact Stacked Homes article yet, which isn't surprising given it was published only two days ago.

However, there is already a sizeable Singapore Reddit discussion around the same underlying theme: Singapore competing for wealthy capital against Hong Kong and Dubai.

One recent r/singapore discussion about Singapore's wealth-hub position generated 233 upvotes, with commenters debating whether attracting wealthy clients actually benefits ordinary Singaporeans. (Reddit)

A recurring sentiment is essentially:

"Great for Singapore's economy, but does the average Singaporean benefit?"

Another discussion about DBS expanding wealth centres attracted 176 upvotes and produced a very similar reaction: commenters highlighted the increasingly K-shaped economy, questioning whether wealth-management growth benefits the broader population. (Reddit)

There's also scepticism about financial-centre rankings themselves. In another Singapore finance discussion, commenters questioned the methodology and incentives behind different global financial-centre rankings. (Reddit)

HardwareZone

I found older Stacked Homes discussions on HWZ rather than a meaningful thread about this particular article. The tone is much more grounded in ordinary Singapore housing economics.

For example, an earlier Stacked Homes housing discussion generated comments along the lines of:

property prices rising faster than salaries

and complaints about the increasing gap between housing prices and ordinary incomes. (HardwareZone Forums)

That's an important contrast.

Savills/Stacked:
Singapore is an increasingly attractive wealth hub.

EDMW-style perspective:
"Okay, but can ordinary Singaporeans afford the property?"

Those are actually two different questions.

X / Facebook / Instagram / TikTok / Threads

I found very little indexed discussion specifically around the Stacked Homes article on these platforms so far. There is, however, broader professional/social amplification of the Savills finding.

Stacked itself has posted the story on LinkedIn, highlighting Singapore's #1 APAC / #6 global position and the shift towards diversified portfolios. (LinkedIn)

Savills Singapore has also promoted the finding, with its messaging focusing on Singapore's connectivity, financial infrastructure and ability to support long-term capital planning. (Savills Singapore)

So at this stage, professional/property/wealth circles appear considerably more interested than mainstream Singapore social media.


🧠 My interpretation

There are actually three different stories hiding inside this article.

1. 🇸🇬 Singapore's position as a wealth hub — very positive

This is probably the strongest part.

Being #1 in APAC and #6 globally is meaningful, particularly because Singapore beats Hong Kong, Tokyo, Shanghai, Bangkok and Kuala Lumpur in the index. (Savills Singapore)

Singapore isn't simply attracting wealthy individuals because of low taxes.

It has developed an ecosystem around wealth:

banks → family offices → lawyers → accountants → fund managers → property → education → healthcare → regional business connectivity

That ecosystem is difficult for another city to replicate quickly.


2. 🏠 Singapore property — positive, but selective

I wouldn't extrapolate this into "buy any Singapore condo."

Instead, it potentially strengthens the case for:

Prime + scarce + well-connected + high-quality + internationally desirable

rather than:

mass-market condo + lots of competing supply

This distinction is particularly important because the next generation has more investment alternatives.


3. 👨‍👩‍👧‍👦 Ordinary Singaporeans — mixed

This is where the social reaction becomes more interesting.

A country can simultaneously have:

more millionaires + stronger wealth-management industry + higher property values

while younger middle-class Singaporeans feel less wealthy.

That isn't hypothetical. Business Times recently described precisely this phenomenon as Singapore's "S$1 million National Day paradox" — rising household wealth alongside anxiety among younger Singaporeans. (The Business Times)

And CNA reported earlier this year that Singapore's wealth inequality is higher than its income inequality, with property and CPF forming major components of household wealth. (CNA)

So the article could actually reinforce an existing social divide:

"Singapore is becoming an even better place for wealthy people."

versus

"Yes, but is it becoming a better place for the average young Singaporean?"


📊 My scores

DimensionScore / 10Why
Positive sentiment8/10Singapore #1 APAC is a strong headline
Negative sentiment4/10Main concern is inequality / property affordability
Social-media controversy3/10Very little discussion of this exact article so far
Economic significance8/10Wealth migration and succession are genuinely important
Singapore property impact7/10Positive structural signal, particularly for prime property
Impact on ordinary households5/10Indirect rather than immediately actionable
Investment usefulness6/10Useful macro signal, but not a buy/sell indicator
Overall article impact7/10Important trend, but Stacked's property interpretation is stronger than the evidence for broad property appreciation

⭐ Overall sentiment: 7.5/10 positive

⭐ Overall impact: 7/10

My bottom line: this is a good-news article for Singapore's wealth ecosystem, but I wouldn't treat it as a bullish signal for all Singapore property.

The more interesting takeaway is actually this:

Singapore is competing to retain wealthy families, not merely attract wealthy individuals.

And that means the next 10–20 years could see increasing demand for Singapore's financial services, education, healthcare, luxury retail, prime housing and family-office ecosystem.

But there's an ironic twist: the same report says the next generation is diversifying away from property. So if you're looking at this from an investment perspective, I would pay more attention to the wealth-management/financial-services trend than simply concluding "Singapore condos will go up." (The Business Times)

For someone following Singapore investments/property, I'd classify this as "structurally bullish for Singapore, selectively bullish for property, and not directly actionable as a property-buying signal."