Labels

Lifestyle (460) Investing (404) Entertainment (305) Singapore (262) Technology (150) Rewards (137) Insights (129) Gaming (105) Equities (97) AI (90) Data (86) Food (85) U.S. (77) Sports (74) Crypto (73) Travel (66) Portfolio (55) News (51) Credit Card (38) Earnings (36) Football (35) Movies (35) Savings (34) Property (29) Policies (27) Tennis (25) Shows (24) Holidays (23) Promotions (19) Bonds (16) Toys (16) Malaysia (15) World (15) REITs (14) T-Bills (12) Apps (11) China (11) Healthcare (10) Referral (10) Currency (9) Anime (8) DeFi (8) Retirement (8) CPF (7) Cash Management (7) Security (6) ETFs (5) Miles (5) Shopping (5) Commodities (4) Robotics (4) Weird (4) platform (4) Cashback (3) Insurance (3) Japan (3) Blog (2) Reviews (2) Robo-Advisor (2) 1-For-1 (1) Asia (1) Australia (1) Banking (1) Funds Management (1) Futuristic (1) Government (1) Indonesia (1) Inflation (1) Interesting (1) Nerfs (1) SGD (1) SSB (1) Social (1) Thailand (1)
Showing posts with label Insights. Show all posts

Friday, 9 October 2026

Gaming Updates: ‘It’s Difficult To Justify the Investment’ – How MMORPGs Built (and Lost) the Live-Service Throne


Source:


ChatGPT:


IGN: How MMORPGs Built and Lost the Live-Service Throne

Article by Matt Purslow · October 2026

The big idea: MMORPGs pioneered the live-service business model, but the gaming industry has shifted towards shorter, more accessible gaming sessions and platforms such as Roblox, Fortnite and Call of Duty. The article argues that MMORPGs haven't disappeared; rather, other games have taken over their role as the centre of online gaming communities.

Top Tech News

1. Article summary

How MMORPGs built the live-service model

Games such as Ultima Online, EverQuest and World of Warcraft established many of the principles now used by live-service games:

  • Persistent virtual worlds that continued evolving after launch.

  • Subscription fees and other recurring revenue models.

  • Communities that developed organically through guilds, quests and raids.

  • Long-term relationships between players and the game world.

The key innovation was that these games weren't merely something players logged into for a match. They were places where people built friendships, reputations and sometimes even romantic relationships.

Why MMORPGs lost their throne

1. The time commitment became harder to justify

Traditional MMORPGs can require hours of questing, levelling and coordinating raids. Modern audiences increasingly favour shorter sessions that fit around busy schedules.

2. Other live-service games became more accessible

Games such as Fortnite and Apex Legends offer quicker gameplay loops. Players can jump in for a match without committing to a persistent character, guild or long progression system.

3. Communities moved beyond individual games

Social media, streaming and creator platforms now host much of the community activity that once happened inside MMORPG worlds. Roblox goes further by allowing players to create and monetise their own experiences.

4. New MMORPGs are expensive and risky

Modern players expect high-quality graphics, huge worlds and years of support. That raises development costs and makes it difficult for new games to compete with established franchises.

What still makes MMORPGs special?

The article highlights three principles drawn from veteran developers:

  • Innovate instead of simply copying successful games.

  • Build worlds that players genuinely care about and feel ownership of.

  • Listen to players and respond to what they want.

The genre still has enduring successes, including World of Warcraft and Final Fantasy XIV. The article also points to new projects such as Guild Wars 3, suggesting that MMORPGs may have a future if developers can solve old problems rather than merely recreate the past.

2. Social media and forum reaction

My search found meaningful discussion about the broader MMORPG decline, although I couldn't verify a large number of posts specifically reacting to this exact IGN article. The following is therefore a sentiment analysis of related discussions, not a claim that these users read the article.

Reddit — nostalgic, frustrated, but still hopeful

Strongest evidence of community discussion

In r/MMORPG's discussion of the state of the genre, players lament the lack of new MMORPGs that capture the spirit of older classics. Some blame monetisation; others point to the enormous development costs and difficulty of producing a game that can compete with established titles.

A separate thread on waiting for a genuinely new MMO attracted thousands of votes, reflecting significant interest in the genre's future.

Sentiment: 7/10 negative towards the current state of MMORPGs, but still hopeful about the right new game.

HardwareZone — the genre's decline is not a new concern

In the 2017 Southeast Asian MMORPG discussion, players already complained about the lack of compelling new PC MMORPGs. A 2024 Singapore MMORPG thread shows continued interest in the genre. More recently, a 2026 EverQuest Legends thread demonstrates that classic MMORPGs still attract attention.

Sentiment: 6/10 negative towards the shortage of fresh experiences, with interest in classic-style games remaining.

X — no reliable article-specific sentiment sample

I couldn't establish a sufficiently reliable set of public posts discussing the exact IGN article. Developer interviews and announcements about MMO projects are relevant to the debate, but they are not evidence of reactions to this article.

Sentiment: unscored, owing to insufficient verified posts.

Facebook — insufficient verified public discussion

I couldn't confirm a representative collection of public comments about the article. Private gaming groups may have relevant conversations that aren't indexed by search engines.

Sentiment: unscored.

Instagram and TikTok — nostalgia is a relevant theme, but direct evidence is limited

Short-form gaming content often lends itself to retrospective discussions of classic MMORPGs and comparisons with today's multiplayer games. However, I couldn't verify enough posts about this particular article to determine audience sentiment.

Sentiment: unscored.

Threads — insufficient verified discussion

No representative set of article-specific public reactions could be confirmed in the results I found.

What the discussion tells us

Three themes stand out from the Reddit and HardwareZone discussions:

  • Nostalgia is powerful: players miss the sense of adventure, social bonds and persistent worlds associated with older MMORPGs.

  • Trust has weakened: players are wary of expensive launches, aggressive monetisation and games that lose support soon after release.

  • Demand hasn't vanished: discussions about World of Warcraft, EverQuest and upcoming MMORPGs show that the genre still has a dedicated audience.

3. Sentiment and impact scores

These scores are my editorial judgement, not measured engagement statistics.

Article's sentiment

7/10

Reflective and somewhat pessimistic about the genre's decline, while recognising the lasting success of older games.

Gaming community interest

8/10

A highly relatable subject for MMORPG veterans and players interested in the future of online gaming.

Verified article-specific traction

3/10

Insufficient evidence of widespread direct discussion of this specific article. This is an evidence score, not a measured popularity score.

Potential industry impact

6/10

Useful industry commentary, but unlikely on its own to change developer strategy or consumer behaviour significantly.

4. My verdict

Overall article impact: 6.5/10.

The article's strongest insight is that MMORPGs didn't simply lose because newer games became more exciting. They lost some of their cultural dominance because the way people play, socialise and create content has changed.

The important nuance is that MMORPGs may have lost the throne without losing their relevance. World of Warcraft and Final Fantasy XIV demonstrate the staying power of persistent worlds, while Roblox illustrates how player-created experiences can expand the live-service model beyond a single developer-controlled game.

For a gaming or technology blog, this is a good topic because it combines nostalgia, business strategy and a question that invites debate: Do gamers still want a world to live in, or just a game to jump into?

My suggested headline for a short-form post would be: “MMORPGs invented live-service gaming. So why did Fortnite and Roblox take their crown?”
Property Updates: REITs vs Physical Property: Why Buying a Singapore Condo in 2026 Might Be a Bad Financial Move


Source:


ChatGPT:


Singapore condo vs REITs in 2026: Article summary and online sentiment

The central question is whether buying a Singapore condominium in 2026 is a better financial move than investing the same money in REITs. The key distinction is between owning a leveraged, illiquid physical property and holding a diversified, income-generating property portfolio through listed securities.

For Singapore investors, this is not simply a question of which asset produces higher returns. It also depends on stamp duties, mortgage costs, rental yields, capital appreciation, liquidity and whether the property is for personal use or investment.

1. What the article says

The author compares a S$1 million investment condo with a portfolio of five Singapore-listed REITs.

The key numbers

Physical condo

S$35,000

Annual gross rent at 3.5% yield

Five-REIT portfolio

S$58,400

Annual distributions at 5.84% yield

The article's estimates for S$1 million invested; actual income and total returns can vary.

ComparisonS$1 million condoS$1 million in REITs
Initial capitalS$277,600, including down payment, stamp duty and legal feesS$1,000,000
Assumed 10-year asset valueS$1.28 millionS$1 million
Estimated 10-year incomeS$220,000 net rentS$584,000 distributions
LiquidityLowHigh
ManagementTenants, repairs and property administrationProfessional management

The five REITs selected

CapitaLand Integrated Commercial Trust (CICT)

Retail and offices · 5.2% trailing distribution yield

CapitaLand Ascendas REIT (CLAR)

Business parks and industrial properties · 6.8%

Mapletree Industrial Trust (MIT)

Industrial properties and data centres · 6.8%

Mapletree Logistics Trust (MLT)

Logistics facilities · 6.6%

Parkway Life REIT (PLife REIT)

Healthcare properties · 3.8%

Yields reported by the article as at 8 October 2026. Past distributions are not guaranteed future income.

The author's conclusion

  • REITs win on flexibility: you can buy smaller amounts, diversify across property sectors and sell units much more easily.

  • REITs win on income in this example: the portfolio's estimated distributions are substantially higher than the condo's estimated net rental income.

  • Condos retain a leverage advantage: a mortgage lets you control a larger asset with less upfront equity, magnifying gains if property prices rise.

  • Condos have additional friction: stamp duties, interest, maintenance, vacancies, agent fees and selling costs can materially reduce returns.

The article does not claim that condos are always bad investments. Its argument is that buying one purely for investment may be less attractive than investors assume.

2. What are people saying on forums and social media?

I searched for discussion across Reddit, HardwareZone and public web-indexed results for X, Facebook and Threads. I could not verify a substantial, article-specific discussion across these platforms, so the findings below are broader reactions to the same investment question, not a count of reactions to this particular article.

Reddit — scepticism about property investment costs

Relevant discussions from September 2026

In r/singaporefi: Is being a landlord better than stock?, commenters discuss taxes, landlord responsibilities and the appeal of dividend income. Another discussion on whether buying a condo is really investing questions whether rental income justifies the capital committed and ongoing costs.

Reddit

Overall reaction: receptive to the article's argument, but not proof that REITs will deliver better total returns.

HardwareZone — compare the actual net yield

In a discussion about buying a condo to rent out, participants question whether a roughly 3% net rental yield justifies the investment without capital appreciation. Other comments point to stamp duties, repairs and vacancies as costs that can erode returns.

HardwareZone Forums

A counterpoint is that property leverage can increase equity returns when prices rise.

Overall reaction: sceptical of low-yield rental properties, but divided on the value of leverage.

X — insufficient verified article-specific reactions

I could not establish a reliable set of posts discussing this exact article. The broader debate is familiar: property appreciation and leverage versus liquidity and income from securities.

Overall reaction: insufficient evidence to assign a platform-specific sentiment score.

Facebook — insufficient verified article-specific reactions

The article links to The Smart Investor's social channels, but that alone does not establish how readers reacted. I could not verify a meaningful sample of public comments on the article itself.

Overall reaction: unconfirmed.

Threads and Instagram — insufficient verified reactions

I could not verify a representative set of posts or comments about this specific comparison. It would be misleading to infer public consensus from the lack of indexed results.

The recurring sentiment in the available Reddit and HardwareZone discussions is that the numbers matter more than the traditional belief that Singapore property always goes up. However, REIT investors also face risks, including falling unit prices, debt refinancing and distribution cuts.

3. Is the article's financial argument actually sound?

My assessment: the central argument is useful, but its 10-year comparison is not a completely fair, like-for-like investment test.

Three important caveats stand out.

1. It compares different amounts of upfront capital

The condo requires S$277,600 upfront in the article's example, while the REIT portfolio uses S$1 million. The condo investor retains the rest of their capital, which could also earn returns elsewhere. Conversely, the condo investor has mortgage repayments and debt outstanding.

A fair comparison should model the same starting equity, account for all cash flows and compare the final net wealth of each strategy.

2. It assumes flat REIT prices

The article assumes the S$1 million REIT portfolio remains worth S$1 million after 10 years, despite paying distributions. This makes the comparison useful for illustrating income, but it is not a forecast of total returns.

REIT prices could appreciate or decline. Similarly, condo prices could rise faster or slower than the assumed 2.5% annually.

3. The yield comparison needs careful interpretation

The article's 5.84% REIT distribution yield is based on five selected trusts, not the entire REIT market. Distributions are not guaranteed, and higher yields can reflect higher risk.

The condo's 3.5% gross rental yield also isn't directly comparable with a REIT's distribution yield, which is paid after expenses at the trust level. A more complete comparison should include the condo's net rental yield, financing, taxes and capital appreciation.

For additional context, a recent Singapore property analysis puts median gross condo rental yield at approximately 3.3% in Q2 2026, before expenses. That supports the article's general concern about rental yields, although individual properties vary considerably.

4. Sentiment and impact scores

These are my editorial assessments, not measured social-media poll results.

Article sentiment

7/10

Positive towards REITs relative to investment condos; critical of the costs of direct property ownership.

Likely investor interest

7/10

A relatable question for Singaporeans weighing a second property against income-producing investments.

Verified online traction

3/10

Limited verified discussion specifically about this article; broader debate exists, but actual reach and engagement are unknown.

Financial decision-making impact

6/10

Useful for prompting a cost calculation before buying a condo, but not sufficiently comprehensive to decide an investment on its own.

5. My verdict

Overall impact: 6.5/10. The article is relevant and thought-provoking, but its headline is stronger than its financial proof.

Its most valuable lesson is that Singapore property investors should not confuse a large asset with a high-return investment. Stamp duties, leverage, rental yield and the opportunity cost of capital all matter.

For someone choosing between a second condo and REITs, I would use this article as a starting point, then compare both investments using the same amount of equity and a realistic range of price-growth, interest-rate and rental-income scenarios.

For further reading:

Wednesday, 7 October 2026

Property Updates: Johor-Singapore SEZ Property Prices Are Up 7–9% — But Investors Still Face One Big Risk


Source:


ChatGPT:


I reviewed the 6 Oct 2026 Stacked Homes article, its underlying Savills data, and the wider Singapore/Johor property discussion. The article is quite nuanced: Johor's JS-SEZ story is improving, but the old oversupply problem has not disappeared. (Property Blog Singapore - Stacked Homes)

🏠 What the article is saying

The headline figures are attractive:

  • JS-SEZ residential prices: up roughly 7–9% YoY

  • Johor overall: only about 2–4%

  • JS-SEZ rental yields: around 6–8%

  • Johor overall: around 5–6%

  • Growth is being supported by corporate/expat rental demand, particularly around major employment and transport nodes. (Property Blog Singapore - Stacked Homes)

The nine JS-SEZ flagship areas include:

JB Waterfront, Iskandar Puteri, Tanjung Pelepas, Tanjung Langsat, Senai-Skudai, Kulai-Sedenak, Desaru-Penawar, Forest City and Pengerang. (Property Blog Singapore - Stacked Homes)

The article's central thesis is that a new type of Johor rental property may be emerging.

Rather than the old speculative "buy condo, wait for Singaporeans/Chinese buyers, sell higher" model, the new opportunity is supposedly:

well-managed properties close to actual economic activity, rented to companies, expats and skilled workers.

That means proximity to:

  • RTS / Bukit Chagar

  • JB CIQ

  • JB City Centre

  • Medini / Iskandar Puteri

  • major industrial/data-centre areas

is becoming much more important than simply buying a cheap condo somewhere in Johor.


⚠️ But the article's real message is the warning

This isn't really a "Johor property boom!" article.

It's more:

"Some parts of Johor are finally working — but don't confuse that with the whole market recovering."

Johor still has a large oversupply of residential units.

The article says around 9,972 unsold units remained in 1H2026, more than twice Kuala Lumpur's unsold stock. (Property Blog Singapore - Stacked Homes)

And there is another problem:

🚧 More supply is coming

Johor is expected to add around 115,000 homes by 2030, with roughly 70,000 in Johor Bahru.

EdgeProp's latest analysis says 609 projects are in the pipeline, with 244 of them in JB. (EdgeProp)

That creates a very interesting contradiction:

Demand ↑
RTS ↑
JS-SEZ investment ↑
Corporate tenants ↑

but simultaneously:

Housing supply ↑↑↑

That's why the article's warning about oversupply is important.


πŸš† RTS is the big catalyst

The RTS is probably the single biggest property catalyst in the story.

It will eventually connect:

Woodlands North ↔ Bukit Chagar

in around five minutes on the rail journey.

The opening has now been pushed to February 2027, according to the article. (Property Blog Singapore - Stacked Homes)

This potentially creates a much larger pool of people who can:

work in Singapore → live in JB

or

work partly in Singapore / partly in Johor → rent in JB

That's especially important for corporate housing.

But Stacked makes an important distinction:

RTS doesn't automatically make every Johor property valuable.

A property 20 km away doesn't suddenly become a five-minute commute.


🏒 The "new asset class"

This is probably the most interesting part of the article.

Savills argues that certain properties could develop into a distinct corporate-rental asset class.

The characteristics are roughly:

✅ Good candidates

  • 1–3 bedroom units

  • within roughly 1–3 km of major employment/transport nodes

  • integrated developments

  • professional management

  • security

  • nearby supermarkets/F&B

  • good connectivity

  • international-school access

  • suitable for executives/expats

Examples mentioned include:

R&F Princess Cove, Suasana Iskandar, TriTower, Paragon Suites, Astake and Eco Botanic. (Property Blog Singapore - Stacked Homes)

❌ Riskier

  • isolated serviced apartments

  • generic investor condos

  • developments far from employment

  • huge developments with thousands of identical units

  • properties whose entire investment thesis is "RTS will make prices rise"

That distinction is extremely important.


πŸ’° The 6–8% rental yield sounds great — but...

This is where I'd be particularly cautious.

A 6–8% gross yield is not the same thing as a 6–8% return in your pocket.

You have:

  • maintenance fees

  • property management

  • agent fees

  • vacancy

  • repairs

  • furnishing

  • taxes

  • potentially higher costs for serviced apartments

  • currency risk

  • resale/liquidity risk

EdgeProp quotes a current market warning that a 6.5% gross yield can potentially become around 4% net after costs. (EdgeProp)

That's a massive difference.

And there's another problem:

You may be buying today's high rent at tomorrow's high property price.

If property prices have already risen 7–9%, your yield on the new purchase price may be considerably less attractive than the yield enjoyed by someone who bought two or three years ago.


🌲 And then there's the Forest City lesson

This is probably the most important historical comparison.

Johor has been here before.

The earlier Iskandar boom attracted huge amounts of speculative capital and massive high-rise development.

Then foreign demand weakened, especially after China's capital controls and changing Malaysian policies around foreign ownership.

The result:

too many apartments + too few genuine residents = enormous oversupply.

Forest City became the most famous example.

And interestingly, even now, CNA reports that Forest City remains a buyer's market, with many sellers but relatively few buyers. (CNA)

So the JS-SEZ story isn't occurring in a vacuum.


πŸ’¬ What are Singaporeans saying?

This is where the article gets particularly interesting.

🟠 HardwareZone: quite sceptical

HWZ's long-running JS-SEZ property discussions are much more bearish than the property industry's marketing material.

Common concerns include:

  • "Another Forest City?"

  • massive oversupply

  • difficulty reselling

  • Malaysian policy uncertainty

  • property management problems

  • foreign ownership restrictions

  • whether Singaporeans really want to live there

  • whether RTS benefits all developments or only the immediate corridor.

One particularly sceptical HWZ comment argues that Singaporeans shouldn't assume property ownership automatically gives them a long-term right to live in Malaysia and suggests renting rather than buying if the objective is simply to live in JB. (HardwareZone Forums)

The thread also has the classic counterargument:

RTS changes the equation because JB becomes much easier to access from Singapore.

So HWZ is basically:

"RTS is real, but don't get caught buying another Forest City."


Reddit: 🟑 cautiously sceptical

The Reddit discussion is similar.

A January 2025 r/SgHENRY discussion on the Singapore-Johor economic zone was quite negative, with concerns about:

  • policy uncertainty

  • corruption/business environment

  • immigration congestion

  • previous JB property failures

  • Singaporeans being marketed condos again. (Reddit)

Another r/singaporefi discussion produced a more nuanced debate.

Some users saw benefits from:

cheaper land + manufacturing + jobs + cross-border economic activity

while others worried about:

job competition + lower Singapore demand + housing effects + whether Johor actually captures the economic value. (Reddit)

And there is a particularly important social dimension: some Johoreans have already expressed concern that Singaporean/foreign buyers are pushing JB housing beyond the affordability of local residents. (Reddit)


πŸ“± X / Facebook / Instagram / TikTok / Threads

There is much less independent discussion of this exact Stacked Homes article on these platforms than on Reddit/HWZ.

The conversation is currently dominated by:

property agents + developers + investors + Malaysia property accounts

rather than ordinary Singaporeans debating the article.

That's significant.

The article is therefore not yet a viral social-media story.

The discussion is still mostly happening among people who are already interested in:

  • JB property

  • RTS

  • JS-SEZ

  • Singapore retirement/relocation

  • Malaysian property investing.


🧠 My interpretation

I'd divide the Johor property story into three buckets.

🟒 1. RTS / CIQ / Bukit Chagar

Most convincing.

This is the part of the thesis I find strongest.

If you are within walking distance/easy access to:

Bukit Chagar → JB Sentral → CIQ → RTS

you have a genuine structural transportation advantage.

The five-minute RTS journey is a real infrastructure improvement.


🟒/🟑 2. Iskandar Puteri / Medini

More complicated.

There are legitimate economic drivers:

  • Legoland

  • international schools

  • healthcare

  • industrial/technology development

  • corporate tenants

But there's also a lot of existing and future supply.

So project selection matters enormously.


πŸ”΄ 3. "Buy anywhere in Johor because JS-SEZ"

I would strongly reject this thesis.

This is where the article's warning about oversupply is most useful.

JS-SEZ is not a rising tide that automatically lifts every condo.

A cheap condo 15–20 km from the actual economic activity may remain a cheap condo.


πŸ“Š My scores

CategoryScore
Overall sentiment6.5/10 positive
Investor enthusiasm7/10
Reddit sentiment5.5/10
HardwareZone sentiment5/10
Property-industry sentiment8/10
Mainstream social-media interest4/10
Controversy5/10
Quality of investment information8/10
Impact on JB property8/10
Impact on Singaporeans considering JB8/10
Immediate buy/sell signal4/10
Long-term significance8/10

⭐ Overall sentiment: 6.5/10

⭐ Overall impact: 8/10

My verdict: This is a more important article than a simple "JB property prices rising" story.

The most useful takeaway is:

Johor may finally be transitioning from a speculative property story to an employment-and-rental-demand story — but only in selected locations.

That's a major difference.

Previously the thesis was:

"Singaporeans/foreigners will buy JB condos → prices rise."

The emerging JS-SEZ thesis is:

"Companies move economic activity into Johor → skilled workers/expats move there → genuine rental demand develops → selected properties become investable."

That second thesis is much healthier.

But I would still be cautious about the numbers because 6–8% gross yield + 7–9% capital growth sounds fantastic precisely when a large amount of new supply is coming. EdgeProp's 2026 pipeline of ~115,000 homes is the number I'd keep at the front of your mind. (EdgeProp)

If I were assessing JB purely as an investment today:

RTS/CIQ walking distance: 🟒 8/10

Strong employment node + quality development: 🟒 7.5/10

Iskandar Puteri/Medini selective buys: 🟑 6.5/10

Generic serviced apartment: 🟠 4/10

Remote condo bought purely for "JS-SEZ appreciation": πŸ”΄ 3/10

And given your family's Singapore base, I'd actually see JB as more compelling for a future lifestyle/second-home/geo-arbitrage option than as a straightforward passive property investment. The article itself provides a good reason: the strongest rental story is increasingly about where the jobs are, not simply where the condos are. (Property Blog Singapore - Stacked Homes)

Investing Updates: New ETFs Coming to SGX: S&P 500, NASDAQ-100 and MSCI World Explained


Source:


ChatGPT:


This is a meaningful development for Singapore ETF investors, and the online reaction is noticeably more substantive than the headline might suggest. The key issue isn't simply "four new ETFs"; it's whether SGX-listed, SGD-traded, Ireland-domiciled UCITS ETFs can become a practical alternative to buying CSPX/VWRA/etc. through LSE/IBKR.

πŸ“° Article summary

The Smart Investor's 6 October article covers four Xtrackers UCITS ETFs from DWS that are scheduled to begin trading on SGX on 13 October 2026. (The Smart Investor)

SGX tickerExposureTERMain attraction
XUSS&P 5000.03%Very cheap US large-cap exposure
EUSS&P 500 Equal Weight0.15%Reduces mega-cap concentration
XNDNasdaq-1000.20%Tech/growth-heavy exposure
XWRMSCI World0.12%Developed-market diversification

All four are Irish-domiciled, accumulating UCITS ETFs, meaning dividends are reinvested rather than distributed. (The Smart Investor)

The headline attraction is that Singapore investors can now buy them in SGD on SGX, rather than accessing the LSE and converting SGD → USD/GBP first.

The tax angle is particularly important

The article argues that Ireland-domiciled ETFs are generally more tax-efficient for Singapore investors than US-domiciled ETFs.

For example, it compares:

S27 — US-domiciled S&P 500 ETF

vs.

XUS — Ireland-domiciled S&P 500 ETF

The article estimates that the combination of lower TER and lower dividend withholding-tax drag could save roughly 0.23 percentage points annually, or around S$230 per year on S$100,000 invested, based on its assumptions. (The Smart Investor)

That's potentially significant over decades.


πŸ”₯ But there's a much bigger story than the article

The real question being discussed online is:

"Should I now buy XUS/XWR on SGX instead of CSPX/VWRA through IBKR?"

And the answer from the investing community is basically:

Maybe — but don't sell your existing ETFs just to switch.

That's the dominant theme I've found.


πŸ’¬ Reddit reaction

This is where the discussion is strongest.

The original r/singaporefi thread announcing the ETFs received 63 upvotes, with substantial discussion around:

  • XUS vs CSPX

  • XWR vs VWRA

  • SRS eligibility

  • SGX vs LSE trading

  • broker fees

  • liquidity

  • bid/ask spreads

  • CDP

  • SGD trading

  • currency risk. (Reddit)

That captures the sentiment quite well.

🟒 What's exciting investors

1. SRS

This may be the biggest practical advantage.

If you're investing through SRS, an SGX-listed ETF provides a much easier route to global equities than going through an overseas exchange. Redditors specifically highlighted the attraction of using XUS/XWR for SRS. (Reddit)

2. SGD trading

No need to manually convert SGD into USD before buying.

But there's an important misconception:

SGD-traded ≠ SGD-hedged.

XUS can be bought in SGD, but you're still exposed to the underlying US stocks and their currencies. (Reddit)

3. Ireland domicile

This retains the key tax advantage that Singapore investors already seek when buying CSPX/VWRA through the LSE. (Reddit)

4. Extremely low XUS TER

At 0.03%, XUS is unusually cheap.

That's even lower than CSPX's 0.07%. (The Kopi Notes)


⚠️ The biggest concern: liquidity

This is probably the single most important criticism.

CSPX has been trading on the LSE for years and has enormous liquidity.

The new Xtrackers SGX counters are starting from scratch on the Singapore trading line.

HardwareZone investors have already raised precisely this concern.

One HWZ discussion notes that S27 has substantially longer trading history and liquidity, while existing Xtrackers SGX listings such as XSG have relatively low volume. (HardwareZone Forums)

So:

XUS TER: 0.03%
CSPX TER: 0.07%

looks fantastic on paper.

But if XUS consistently has a materially wider bid/ask spread, that 0.04% TER advantage can become less meaningful.

That's why I would not automatically declare XUS superior to CSPX yet.

We need to see actual trading volume and spreads after 13 October.


πŸ–₯️ HardwareZone sentiment

The HWZ discussion is surprisingly balanced.

The overall attitude is:

πŸ‘ "This is good."

But followed immediately by:

πŸ€” "How liquid will it actually be?"

One HWZ participant described the growing ETF competition as good for retail investors, while another pointed out that investors shouldn't assume the new SGX ETFs will immediately match established LSE liquidity. (HardwareZone Forums)

Another very interesting HWZ discussion about XWR asks the obvious question:

Why not just have Vanguard cross-list VWRA?

That's telling.

VWRA remains the benchmark in many Singapore DIY portfolios.

XWR isn't equivalent to VWRA:

  • XWR = developed markets

  • VWRA = developed + emerging markets

So somebody moving from VWRA to XWR is actually changing their portfolio allocation, not merely changing the exchange. (HardwareZone Forums)


πŸ“Š Social-media / investing-community sentiment

I searched specifically for discussion around XUS/XWR/XND/EUS across the platforms you mentioned.

Reddit — 🟒 Strongly positive

This is currently the most active public discussion.

The tone is overwhelmingly:

"Interesting."
"Could be useful."
"Especially for SRS."
"Let's see the liquidity."

There is very little outright negativity. (Reddit)

HardwareZone — 🟒/🟑 Positive but pragmatic

More technically minded.

People are thinking about:

  • commissions

  • CDP

  • liquidity

  • bid/ask spreads

  • SRS

  • tax efficiency

  • broker selection.

This is probably the most useful discussion for actual Singapore investors. (HardwareZone Forums)

X / Twitter — 🟒 Positive but limited

There isn't yet a huge mainstream X conversation around the article itself.

The strongest social amplification is from the financial/investing ecosystem rather than ordinary retail investors.

Facebook — 🟑 Limited

I didn't find a significant public discussion specifically around this Smart Investor article.

Instagram — 🟑 Limited

Mostly informational/promotional content rather than detailed investor debate.

TikTok — 🟑 Limited

No meaningful volume of public discussion yet.

Threads — 🟑 Limited

Likewise, not enough discussion to suggest a strong independent sentiment.

Professional social media — 🟒 Strong

SGX itself is actively promoting the listing, emphasising SGD trading and SRS eligibility. (LinkedIn)

So the social-media picture is currently:

Investor forums >>> Reddit > professional social media >>> mainstream social media


🧠 The REALLY important comparison

For a Singapore investor, I'd frame the four ETFs like this:

ETFBest use
XUSCheap S&P 500 core
EUSReduce mega-cap concentration
XNDNasdaq/technology tilt
XWRDeveloped-world core
CSPXEstablished LSE S&P 500 option
VWRADeveloped + emerging global core

And XWR is not a VWRA replacement.

That's one of the biggest points being debated online.


πŸ’° What this means for your portfolio

This article is actually particularly relevant to your investment setup because you've previously looked at Amundi MSCI World, global portfolios, IBKR and Singapore-listed ETFs.

I wouldn't interpret this announcement as:

"Sell existing global ETFs and buy XUS/XWR."

I'd interpret it as:

"Singapore investors now have another potentially excellent accumulation route."

For new money, the calculation becomes much more interesting.

If you want S&P 500

XUS becomes very compelling.

0.03% TER + Ireland domicile + SGD trading + potentially SRS eligibility.

But wait for actual SGX liquidity.

If you want developed-world diversification

XWR is interesting, particularly for SRS/CDP-oriented investors.

But don't confuse it with VWRA.

If you already use IBKR

The advantage is less obvious.

IBKR gives you:

  • LSE access

  • very deep liquidity

  • cheap FX

  • enormous ETF selection.

So the convenience of SGX doesn't necessarily outweigh IBKR's advantages.


πŸ“ˆ My sentiment & impact scores

CategoryScore / 10
Overall sentiment8.5/10 positive
Retail investor excitement8/10
Reddit sentiment8.5/10
HardwareZone sentiment8/10
Controversy2/10
Investment significance9/10
Impact on SGX8/10
Impact on SRS investors9/10
Impact on existing IBKR investors6/10
Impact on beginner investors9/10
Immediate market impact5/10
Long-term significance9/10

⭐ Overall sentiment: 8.5/10 positive

⭐ Overall impact: 8.5/10

My verdict: This is more important than the Smart Investor article makes it sound.

The article is basically a useful explainer, but the underlying development could be one of the more significant improvements to Singapore's retail ETF landscape in years.

The biggest winners are probably:

πŸ₯‡ SRS investors
πŸ₯ˆ Beginners who want global exposure without LSE/FX complexity
πŸ₯‰ Investors who want CDP-held global ETFs

The people who gain the least are experienced IBKR + LSE investors, because CSPX/VWRA and similar ETFs already give them excellent access and liquidity.

And there's one thing I'd watch very closely on 13 October:

XUS's actual bid/ask spread and trading volume.

If XUS develops decent liquidity, its 0.03% TER + Ireland domicile + SGX/SRS accessibility makes it a genuinely serious competitor to CSPX for Singapore investors.

If liquidity is poor, CSPX remains the better practical instrument despite its slightly higher TER.

So I'd call this 8.5/10 impact — but with a big "watch the liquidity" asterisk.

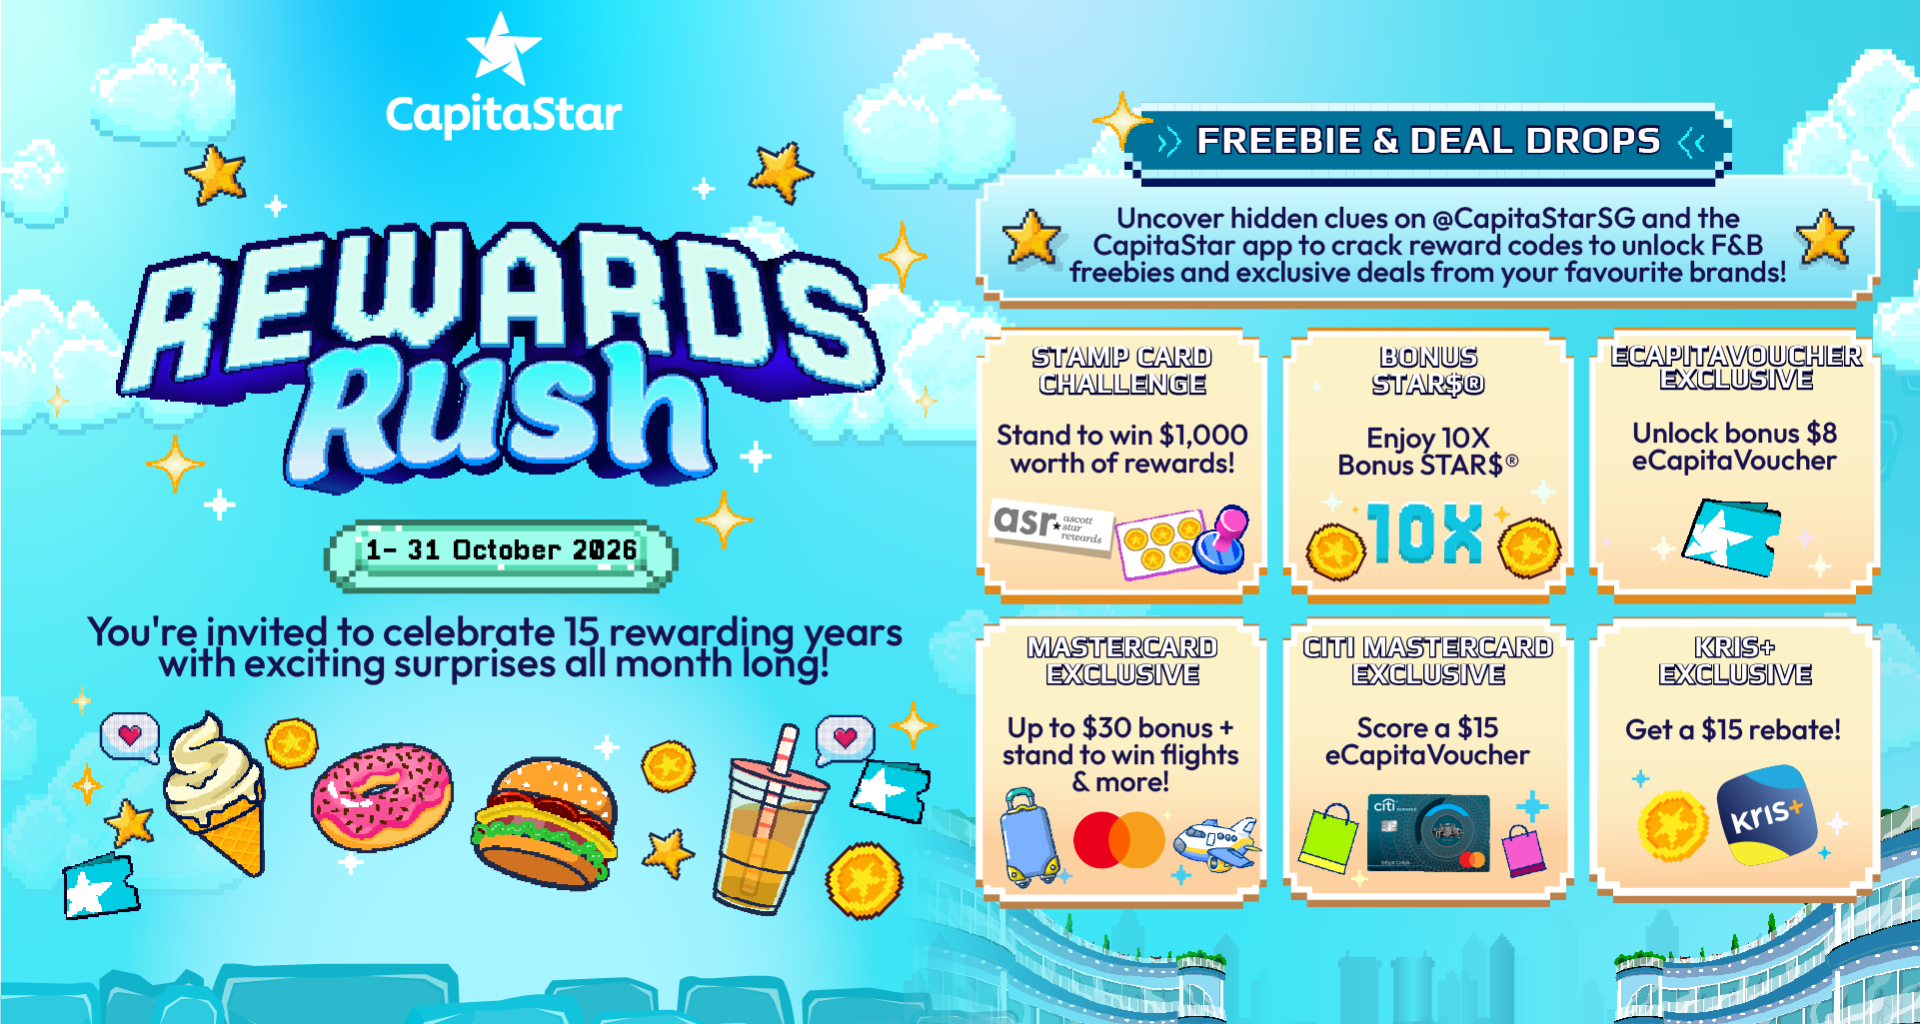
Rewards Updates: CapitaStar Turns 15 with Month-Long October Rewards and New Kris+ Integration


Source:


ChatGPT:


πŸ“° Summary of the article

The Alvinology piece is essentially a promotion/deal roundup for CapitaStar's 15th anniversary, with the biggest development being the new CapitaStar × Kris+ integration. The underlying announcement was made by CapitaLand on 1 October, and the Alvinology article was published 6 October. (Alvinology)

The big news: CapitaStar + Kris+

This is the part I think is most relevant for you as a miles/rewards user.

After linking your accounts, you can now:

Pay with Kris+ → earn KrisPay miles + CapitaStar STAR$ in the same transaction.

Previously, using Kris+ generally meant giving up the ability to earn CapitaStar STAR$ on that transaction. The new integration removes that trade-off. (The MileLion)

There is a S$20 minimum transaction to earn STAR$ when paying through Kris+. (The MileLion)


🎁 October promotions

The article highlights several overlapping promotions.

1. S$150 Kris+ spend → 1,500 KrisPay miles

For 1–31 October 2026:

  • Link CapitaStar + Kris+

  • Spend S$150 in a single transaction

  • At an eligible Kris+ merchant in a participating CapitaStar property

  • Receive 1,500 KrisPay miles, effectively S$15 of Kris+ spending value.

There are 1,000 rewards available. Importantly, these particular 1,500 KrisPay miles cannot be transferred to KrisFlyer; they remain usable within Kris+. (The MileLion)

This is a very important distinction because the Alvinology article's wording about KrisPay/KrisFlyer can otherwise make the promotion look more valuable than it actually is.

2. 10X STAR$

October also gives 10X bonus STAR$ for qualifying S$80+ transactions using eligible linked payment methods, including Kris+. (The MileLion)

MileLion calculates that a S$100 transaction can generate roughly:

  • 500 base STAR$

  • 5,000 bonus STAR$

  • 5,500 STAR$ total

before assigning a value to the Kris+ miles. That's approximately a 5.5% CapitaStar rebate equivalent based on its calculation. (The MileLion)

3. eCapitaVoucher promotion

There is also:

S$80 eCapitaVoucher spend → 10X STAR$ + S$8 eCapitaVoucher bonus. (CapitaLand)

4. Mastercard promotion

Buy S$250 eCapitaVoucher with a linked Mastercard and you can receive up to S$30 bonus eCapitaVoucher plus entry into a lucky draw.

One of the prizes is 80,000 KrisFlyer miles.

Citi Mastercard users can also receive an additional S$15 eCapitaVoucher with S$200 qualifying in-store spend. (CapitaLand)

5. 15th anniversary prizes

15 winners get S$1,000 worth of STAR$ + Ascott Star Rewards points. (CapitaLand)


πŸ”Ž What is the online community saying?

The interesting thing is that this isn't really a mainstream news story. Discussion is concentrated among the Singapore miles/deals/loyalty-programme crowd.

🟒 Miles community: strongly positive

The reaction from the miles sites is clearly favourable.

MileLion's headline is basically:

"You can now double dip on Kris+ miles and STAR$."

Its conclusion is that STAR$ is a modest rebate, but since you're now getting it on top of Kris+ miles, there's little reason not to collect it when the transaction qualifies. (The MileLion)

Mainly Miles similarly describes it as a "double dip", particularly useful for people who regularly shop at CapitaLand malls such as Plaza Singapura, Raffles City and IMM. (Mainly Miles)

Suitesmile is also highlighting the S$15 rebate and how it can be combined with the broader Kris+ October promotions. (Suitesmile)

🟑 Reddit: more mixed

There isn't yet a significant Reddit thread specifically discussing the 6 October Alvinology article.

But there is a very relevant recent r/askSingapore discussion about Singapore loyalty apps. It received 92 upvotes, and the general assessment was that CapitaStar is more of a "collect passively and redeem periodically" programme, while Kris+ is more attractive to people who actively chase KrisFlyer miles. (Reddit)

That's actually a good description of the opportunity here:

CapitaStar alone: mildly interesting.

Kris+ alone: useful mainly to miles enthusiasts.

Kris+ + CapitaStar + suitable credit card: considerably more interesting.

🟑 HardwareZone: historically more sceptical/practical

The long-running CapitaStar thread on HardwareZone has a much more practical tone.

Users have discussed:

  • eCapitaVoucher usability

  • merchants not knowing how to process it

  • technical problems

  • whether STAR$ is worth using

  • changes to earning rules

  • stacking CapitaStar with other reward programmes.

One particularly relevant 2021 discussion reported merchants sometimes being unable to process eCapitaVoucher, while another user said they had never encountered such problems. (HardwareZone Forums)

More recently, HWZ users have complained about changes to CapitaStar earning and the difficulty of stacking it with other programmes. (HardwareZone Forums)

So the HWZ mentality is less:

"Wow, amazing new partnership!"

and more:

"Can I actually stack this with my existing cards/rewards and is the effort worth it?"

That's probably the right way to evaluate this promotion.

X / Facebook / Instagram / TikTok / Threads

I couldn't find a substantial, independently indexed discussion around this particular announcement on those platforms yet.

That's not surprising because the announcement is only about a week old.

There is, however, clear official/social amplification. CapitaLand is promoting the anniversary and Kris+ integration on LinkedIn, while CapitaStar is directing members to its Instagram account for the October treasure-hunt codes. (LinkedIn)

So the social conversation currently appears to be promotion-driven rather than controversy-driven.


πŸ’‘ The part I think matters most for YOU

Given your existing interest in KrisFlyer + credit-card stacking + eCapitaVoucher, I'd actually rate the Kris+ integration more important than the 15th-anniversary celebration itself.

The new stack potentially becomes:

Credit card
↓
Kris+ miles
+
CapitaStar STAR$
+
October promotional bonus
+
potentially other card-specific rewards

That's significantly more interesting than CapitaStar's old model.

However, there's an important catch:

Don't automatically use Kris+ for every CapitaLand purchase.

You still need to compare:

Kris+ miles + STAR$

against what you'd earn using your best credit card directly.

And the biggest trap is the S$150 rebate.

It's not really:

"Spend $150 and get 1,500 KrisFlyer miles."

It's:

"Spend $150 and get 1,500 KrisPay miles that are worth S$15 within Kris+."

Those 1,500 miles cannot be transferred to your KrisFlyer account. (Singapore Airlines)

That's a very different proposition.


πŸ“Š My sentiment & impact score

CategoryScore / 10My assessment
Overall sentiment8.5/10 positiveMostly viewed as extra rewards
Miles-community sentiment9/10Double-dipping is genuinely useful
General consumer sentiment7/10Nice rewards, but requires spending
Controversy2/10Very little controversy
Deal attractiveness8/10Good if you're already spending at CapitaLand malls
KrisFlyer relevance6/10Better than before, but KrisPay ≠ KrisFlyer
CapitaStar relevance9/10Meaningfully improves the programme
Impact on Singapore consumers6/10Useful but not transformational
Impact on miles/points collectors8.5/10This is the target audience
Overall article impact7.5/10Useful deal news rather than major Singapore news

⭐ Sentiment: 8.5/10 positive

⭐ Impact: 7.5/10

My verdict

This is a genuinely useful rewards development, not just a CapitaStar birthday marketing exercise.

The CapitaStar × Kris+ double-dipping is the real story.

For someone who already shops at Lot One, Plaza Singapura, IMM, Junction 8, Tampines Mall, Westgate, etc., the integration gives you another reason to route eligible spending through Kris+.

But I'd rate the S$150 → 1,500 KrisPay miles promotion as good rather than exceptional, because the reward is locked inside Kris+ rather than becoming transferable KrisFlyer miles.

And given your previous strategy of saving your S$1,000 eCapitaVoucher rather than using it unnecessarily, I wouldn't change that strategy just because of this article. The better opportunity is to use new cash/card spending that you were already going to make and stack the rewards.

One particularly interesting angle for you: October 2026 has both the CapitaStar 15th-anniversary promotions and the Kris+ Birthday Bash (including 8 miles/S$1 at 65+ partners), so October is unusually attractive for people who are willing to optimise the payment method. (Singapore Airlines)